Signal and systems miscellaneous
- The mean square power of the power spectral density given is Rx(τ)—
-
View Hint View Answer Discuss in Forum
The mean square power,
Rx(0) = NB sin c 2πBτ= NB sin 2πBτ 2πBτ = NB cos 2πBτ.2πB ⎪τ = 0 2πB
= NB.Correct Option: A
The mean square power,
Rx(0) = NB sin c 2πBτ= NB sin 2πBτ 2πBτ = NB cos 2πBτ.2πB ⎪τ = 0 2πB
= NB.
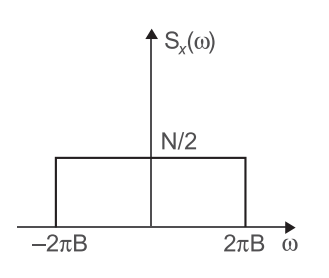
- The power spectral density is shown below then Rx(τ) is—
-
View Hint View Answer Discuss in Forum
Rxx(τ) = 1 
∞ Sx(ω) ejωt .dω 2π 0 Given that Sx(ω) = 
N ;|ω| = 2πB 2 0; otherwise so, Rx(τ) = 1 2πB N · ejωt dω 2π – 2πB 2 = N 
ejωt 
2πB 4π jτ – 2πB = N eej2πBτ – e– j2πBτ 2πτ 2τ = N sin 2πBτ 2πτ = NB sin (2πBτ) 2πBτ {∵sin x/x = sinc x} 2πτ
= NB sinc (2πBτ)Correct Option: A
Rxx(τ) = 1 ∞ Sx(ω) ejωt .dω 2π 0 Given that Sx(ω) = N ;|ω| = 2πB 2 0; otherwise so, Rx(τ) = 1 2πB N · ejωt dω 2π – 2πB 2 = N ejωt 2πB 4π jτ – 2πB = N eej2πBτ – e– j2πBτ 2πτ 2τ = N sin 2πBτ 2πτ = NB sin (2πBτ) 2πBτ {∵sin x/x = sinc x} 2πτ
= NB sinc (2πBτ)
- The joint pdf of random variable x and y is given by fxx(x, y) = ke– (ax + by) u(x).u(y)
-
View Hint View Answer Discuss in Forum
Fxy(x, y) = ∞ ∞ fxy(x, y)dx dy -∞ -∞ 1 = ∞ ∞ ke–(ax + by) u(x).u(y)dy.dx -∞ -∞ 1 = ∞ ∞ ke–ax.e–by.dydx 0 0 1 = k ab
or k = abCorrect Option: A
Fxy(x, y) = ∞ ∞ fxy(x, y)dx dy -∞ -∞ 1 = ∞ ∞ ke–(ax + by) u(x).u(y)dy.dx -∞ -∞ 1 = ∞ ∞ ke–ax.e–by.dydx 0 0 1 = k ab
or k = ab
- If the variance of the random variable X is σ2 x then the variance of – kx is—
-
View Hint View Answer Discuss in Forum
We know that
σ2x = E[x2] – [μx]2= ∞ x2 fx(x)dx - ∞ xfx(x)dx 2 -∞ -∞
Let, new variance,σ2 x′ = ∞ (– kx)2fx(x)dx - ∞ (– kx)fx(x)dx 2 {∵ x′ = – kx} -∞ -∞
orσ2 x′ = k2 ∞ x2fx(x)dx - k2 ∞ xfx(x)dx 2 -∞ -∞
σ2 x′ = k2σ2xCorrect Option: C
We know that
σ2x = E[x2] – [μx]2= ∞ x2 fx(x)dx - ∞ xfx(x)dx 2 -∞ -∞
Let, new variance,σ2 x′ = ∞ (– kx)2fx(x)dx - ∞ (– kx)fx(x)dx 2 {∵ x′ = – kx} -∞ -∞
orσ2 x′ = k2 ∞ x2fx(x)dx - k2 ∞ xfx(x)dx 2 -∞ -∞
σ2 x′ = k2σ2x
- The spectral density of random process, where
Rxx(τ) = Ke– 3|τ|
-
View Hint View Answer Discuss in Forum
NA
Correct Option: B
NA

